New perspectives on an ever-changing funding landscape
Executives from Screen Australia, Unifrance, ICEX, Screen Ireland and Norway’s NFI discuss how the funding landscape is changing, their new priorities and how they are adapting to an evolving industry.
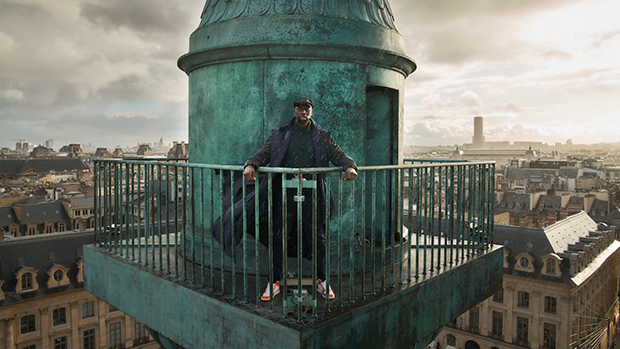
Shows like Lupin set a benchmark for french sales
The financial architecture underpinning international television production has entered a period of recalibration, with established incentive regimes demonstrating both resilience and vulnerability as the industry adjusts to dramatically reduced commissioning volumes following the contraction from peak TV levels.
Across multiple territories, the frameworks designed to attract production investment and support local creative industries are being tested by tighter budgets, more selective commissioning and evolving financing structures that increasingly resemble independent film models rather than the flush streaming era that preceded them.
Australia’s incentive system, for instance, remains among the most substantial globally, with the Producer Offset administered by Screen Australia generating certificates worth A$713m (US$464m) across 213 projects in 2024-25, representing total film expenditure of A$2.3bn. The scale reflects what Grainne Brunsdon, chief operating officer at Screen Australia, characterises as punching “well above our weight on the world stage, ” citing shows such as Bluey, Narrow Road to the Deep North, Colin from Accounts and Heartbreak High.

Grainne Brunsdon
Lisa Maree Williams
However, Brunsdon emphasises that the country’s competitive advantage is not just about the financial mechanisms themselves, arguing: “Australia brings enormous value to the table that goes well beyond world-class incentives. Our strength is in our talent, ideas and a point-of-view that has evolved from our distance, our landscape, our First Nations storytellers and the experiences of the people who make Australia their home.”
The contraction from peak TV levels has not diminished production volumes in Australia, with Brunsdon noting that “production levels continue to grow in Australia with production costs and budgets under pressure.”
However, the changing environment has prompted Screen Australia to adjust its approach, announcing changes to scripted content and documentary funding programmes “to better support screen practitioners and future-proof against industry and audience disruption.” The modifications prioritise “funding producers with strong ideas and a clear pathway to audience,” reflecting a shift towards more marketplace-oriented evaluation criteria. In 2024-25, development and production funding was prioritised with 86% of total available funding directed into content.
Ireland has similarly increased investment in television drama production, with Désirée Finnegan, CEO at Screen Ireland, noting that “between 2019 and 2021, spend in local TV drama production increased by 40% and has increased further since then.” Screen Ireland supported 10 new series as part of its 2025 slate, including Mix Tape, The Walsh Sisters and Irish Blood, maintaining what Finnegan describes as “a dual approach to industry development, one that maintains a balance between Irish and international projects.”
The country’s tax incentive covers all goods and services spent during production in Ireland, including cast, crew, post-production and visual effects work undertaken locally. Ireland has also introduced the Nationwide Additional Production Fund, offering additional support to productions filming outside the central production hub, alongside funding strands focused on sustainability initiatives.

The Irish incentive structure incorporates mandatory skills development requirements, with productions needing to provide opportunities for structured work-based learning to qualify for Section 481 certification. This requirement, introduced in 2019, reflects what Finnegan characterises as an essential pairing of Ireland as a location for international productions with high-quality skills development. Screen Ireland has established five National Talent Academies designed to develop diverse talent and crew bases across film, television, animation and visual effects, while over 150 mentees have participated in the Screen Mentoring scheme pairing new talent with experienced industry mentors.
Norway’s production incentive has proven highly effective in attracting international productions despite budget limitations that constrain its full potential. Kjetil Omberg, director of production and international relations at the Norwegian Film Institute (NFI), confirms that “we receive many applications and fill the quota every year – and could easily accommodate many more international productions.” The country’s reputation for skilled crews and strong infrastructure supports demand that exceeds available incentive funding, with Omberg adding: “The challenge is that the incentive budget is limited, so there is significant potential if the framework were expanded. There is strong demand from the industry for this expansion to remain competitive with other markets.”
The post-peak TV environment has manifested differently across these territories. While Norway has exported its own hits like Skam, Zombie Lars, Kids in Crime, Requiem for Selina and Shut Up!, Omberg describes how “the industry experienced a serious dip as the market adjusted following the major streamers’ reduced investment,” though the sector is “now slowly seeing an upward trend again” with more projects in production compared with the previous year. The financing landscape has fundamentally shifted, with “more coproduction within the Nordic region and across Europe” and financing now resembling “the independent film model more than before and the process takes longer.” Production patterns have polarised, with “more low-budget projects alongside high-end productions, but overall, there are fewer projects than there were at the peak.”

After the heady days of Money Heist, Elite and The Ministry of Time, Spain has also responded to the end of peak TV through “a more selective commissioning environment, where quality and international appeal are paramount,” according to Luis Mayoral Gabaldón, director of cultural industries at ICEX Spain Trade & Investment. Spanish producers have adapted by “focusing on fewer, more ambitious projects, often with international partners, and by leveraging Spain’s strong track record in storytelling and production value to remain competitive.” The implementation of the Spain Audiovisual Hub of Europe plan by the Spanish government has reinforced the country’s positioning, with Mayoral noting that Spain “has positioned itself as a key player in recent years” with the trend “undoubtedly being reinforced” by the government initiative.
France’s support mechanisms have certainly helped mitigate economic challenges, with Sarah Hemar, director of audiovisual at Unifrance, observing: “France is fortunate to have a diversity of support mechanisms, from CNC subsidies to regional funds and tax incentives, which strengthen our position as valuable coproduction partners.”
After a few years when shows like Lupin, The Bureau and Call My Agent were driving sales, French producers face challenges “very much aligned with those of their international peers – selling and funding remain front of mind,” with rising costs and competitive marketplace conditions making financing complex. However, Hemar argues that “our strong institutional framework and international networks give us some advantage.”
The French coproduction landscape demonstrated significant volatility before recovering strongly. After three consecutive years of growth in foreign pre-financing between 2019 and 2021, a sharp decline was recorded in 2022 with levels falling 44.6% to €105.1m, remaining stable in 2023 at €105.8m. In 2024, foreign pre-financing rose 81% to €191.6m, reaching its highest historical level and exceeding the decade’s average by 42.9%. The increase was driven by both coproduction contributions, up 58.7% to €116.2m, and foreign pre-sales, which more than doubled with 131.2% growth to €75.4m. Hemar describes international coproduction as “a crucial strategy for resilience and growth” in an unpredictable landscape shaped by business disruptions and geopolitical tensions.

The strategic importance of coproduction has intensified across multiple territories as a response to constrained commissioning environments. Spain has become “a strategic partner in European coproductions, thanks to its creative talent, robust production infrastructure, and competitive incentives,” according to Mayoral, with rising collaborations with France, Germany and Italy particularly in drama and documentary formats. Spanish companies are “not only contributing locations and services, but also taking part in development and creative leadership, reinforcing Spain’s role as a central player in the European audiovisual ecosystem.”
Nordic collaboration has strengthened through initiatives including New8 and the Scandi Alliance, with Omberg noting that “new coproduction constellations are emerging” as financing structures evolve. However, he emphasises that much collaboration “happens naturally through existing industry networks” with broadcasters and producers maintaining “well-functioning partnerships across the Nordic region.” The NFI’s role centres on facilitation, with Omberg explaining: “We don’t set the agenda for Nordic TV partnerships, the industry does – but we try to enable and support where we can.”
Australia issued six provisional and four final official coproduction certificates in the most recent period, with territories including Canada, Ireland, New Zealand and the UK representing primary partnership countries. Brunsdon acknowledges “enormous potential for growing the number of coproductions and we would love to see more of these collaborations,” highlighting both strong global appetite for Australian content and opportunities for expanded partnership activity.

The challenges facing producers extend beyond purely financial considerations into fundamental questions about competitive positioning in an increasingly fragmented attention economy. Norwegian producers are “competing not only with traditional TV but also with ultra-short content on social media and YouTube and reality shows,” according to Omberg, while broadcasters are “acquiring content in new ways” within a shifted competitive environment. Spanish producers confronted “a highly competitive global market, marked by tighter budgets and increased pressure to deliver internationally viable content” in 2025, alongside “the slowdown in commissioning from major platforms and the fragmentation of audiences” requiring adaptation of business models and exploration of new financing and distribution strategies.
Regional production development has emerged as a strategic priority for multiple territories seeking to build sustainable creative economies beyond established production centres. Ireland has made regional production “a key priority in growing Ireland’s screen industries into the future,” according to Finnegan, with initiatives required “to support creative talent and to build permanent skilled crew bases in different locations.” The Nationwide Additional Production Fund represents one mechanism for incentivising production outside Dublin’s central hub, though Finnegan says further investment in regional infrastructure and skills development are essential for discovering “cultural potential across the entire country.”
Australia similarly encourages production activity across diverse locations, with Brunsdon highlighting how “our distance, our landscape, our First Nations storytellers and the experiences of the people who make Australia their home” contribute to distinctive creative perspectives that underpin international appeal. Screen Australia’s corporate plan includes focus on “empowering the industry with insights and resources to stay ahead in a dynamic market” through renewed emphasis on audience insights and market intelligence.
The integration of emerging technologies and formats presents both opportunities and challenges for incentive structures designed primarily for traditional production models. Nevertheless, Screen Ireland has supported 38 innovative projects through its Innovation in Storytelling Development Fund since 2021, covering immersive storytelling, virtual reality, augmented reality and app development, while expanding the remit to support the digital games industry. Finnegan emphasises “the importance of research, education, training and skills development” in responding to emerging creative technologies whilst maintaining that “we believe in the enduring power of cultural storytelling on screen.”
Narrow Road to the Deep North
The effectiveness of incentive regimes ultimately depends on their ability to support sustainable creative industries capable of adapting to rapidly evolving market conditions while maintaining distinctive cultural voices. Brunsdon argues that Screen Australia takes seriously its “role in building a vibrant, viable screen industry that reflects the depth and diversity of Australian stories,” encouraging producers and filmmakers to “seek out different ways to tell their stories and innovative ways to finance their projects” within the evolving landscape. The agency’s unique position allows it to “foster both talent and IP from the beginning of development through to platform distribution or a direct-to-audience pathway.”
What emerges across these territories is recognition that financial incentives, while necessary, prove insufficient without accompanying investment in skills development, infrastructure, market intelligence and strategic positioning within international coproduction networks. The post-peak TV environment has not diminished the importance of production incentives but has intensified scrutiny of how effectively they support creative industries navigating more challenging market conditions, longer financing timelines and fundamentally altered relationships between producers, commissioners and audiences.
The territories demonstrating greatest resilience combine competitive financial frameworks with strategic investment in talent development, regional infrastructure and international partnerships that position their creative industries for sustained viability rather than dependence on cyclical commissioning patterns from global platforms.